Who Pays Closing Costs When You Buy a Home in Maryland?

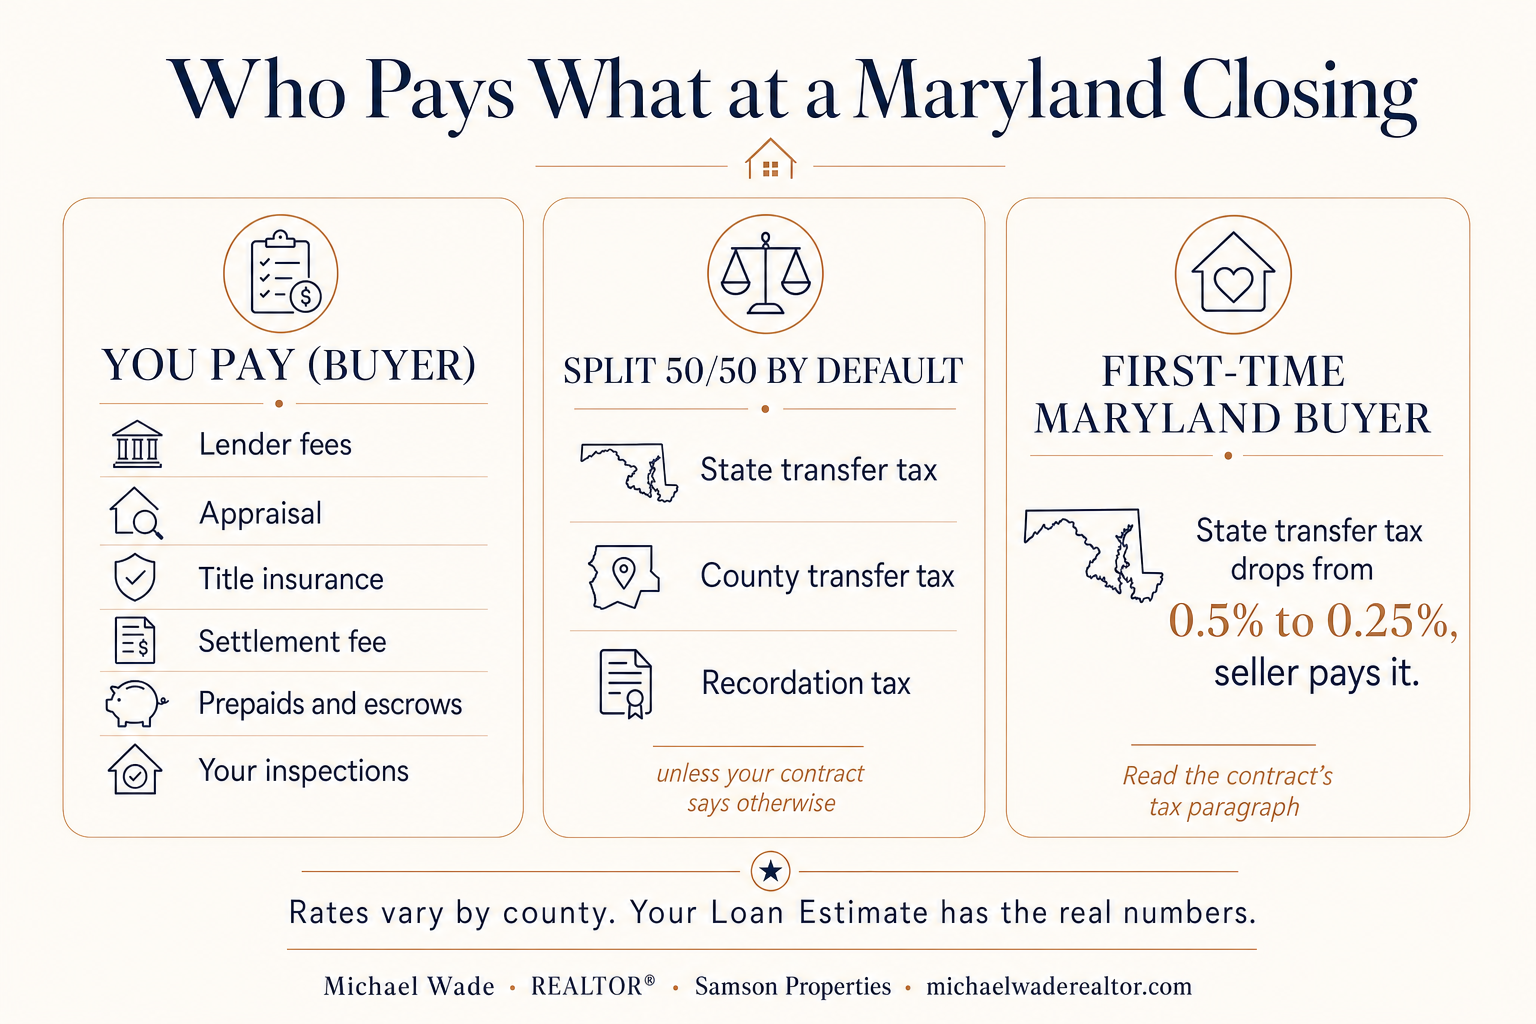
Short answer: You'll pay most closing costs, but not all of them. In Maryland, the state transfer tax, the county transfer tax and the recordation tax are split 50/50 between buyer and seller unless your contract says something different. Lender fees, title fees and prepaid items are the buyer's. If you're a first-time Maryland buyer, the rules shift in your favor, and it's worth knowing how before you write an offer.
If the closing cost number on your Loan Estimate made your stomach drop, you're not alone. "Hidden fees" is one of the most common worries I hear from buyers. Let's take the mystery out of it.
The two buckets of closing costs
Bucket 1: Costs tied to your loan and the purchase. These are on you as the buyer:
- Lender fees (origination, underwriting, credit report)
- Appraisal
- Title search and title insurance (lender's policy is usually required; owner's policy is optional but worth a conversation)
- Settlement fee from the title company
- Prepaids and escrows: homeowners insurance, a few months of property taxes, and interest from settlement to the end of the month
- Your own inspections
Every one of these varies by lender, title company and loan type. Your Loan Estimate is the real number, not a rule of thumb. Compare Loan Estimates from at least two or three lenders.
Bucket 2: Maryland deed taxes. When a home sells in Maryland, three taxes are due: a state transfer tax (0.5% of the price), a county transfer tax in most counties, and a county recordation tax. Maryland law presumes buyer and seller share these equally unless the contract says otherwise (Real Property Article 14-104). Competitive offers sometimes shift more to the buyer, and slower markets sometimes shift more to the seller.
What it can look like by county
Rates change, so treat these as ballpark numbers and have your title company confirm the rate for your settlement date. Based on fiscal year 2026 rates compiled from Maryland Department of Legislative Services data, total deed taxes on a $400,000 home with no exemptions run roughly:
- Frederick County: about $7,600
- Anne Arundel County: about $8,800
- Howard County: about $9,000
- Montgomery County: about $9,560
- Prince George's County: about $9,800
- Baltimore County: about $10,000
- Baltimore City: about $12,000
Your half is roughly half of those figures. [VERIFY: county rates against each county's finance office or your title company before publishing; source: jungmarker.com/guides/maryland-closing-costs-by-county, citing DLS FY2026.]
What first-time Maryland buyers should know
If you've never owned a home in Maryland that was your principal residence, and you'll live in this one, the state transfer tax drops from 0.5% to 0.25%. Maryland's clerks of court describe this as a first-time Maryland home buyer rate, and each buyer on the deed signs a statement under oath to claim it. On top of that, state law says the seller pays the recordation tax and county transfer tax for a first-time buyer unless the contract expressly says otherwise.
Here's the catch. Many contracts do address this directly, so read the tax paragraph closely and ask me or your agent to walk you through it before you sign. [VERIFY: confirm current treatment in the Maryland REALTORS contract and with a title company.]
Some counties have their own exemptions too. For example, Montgomery County exempts the first $100,000 of the price from recordation tax for owner-occupants, and Baltimore City has a small exemption for owner-occupants. Ask your title company whether your purchase qualifies. [VERIFY.]
Ways to bring your closing costs down
- Ask for a seller credit. In a balanced market, sellers will sometimes agree to cover part of your costs. The money goes in the contract in writing, and your lender has limits on how much credit it allows.
- Shop lenders. Fees and rates can differ more than people expect.
- Look at the whole picture. A lower rate with higher fees isn't always the better deal, and the reverse is true too.
- Ask about assistance programs. Maryland has down payment and closing cost help for eligible buyers. [VERIFY current programs and income limits at Maryland Mortgage Program before you quote anything.]
- Time your closing date. Prepaid interest depends on the day of the month you close.
What I'd do in your shoes
Get a Loan Estimate early, before you fall in love with a house. Ask for the cash-to-close number, not just the monthly payment. Then plan for a little cushion, because the final figure can move.
If you want a second set of eyes on your estimate, I'm happy to look it over. You can book a free 15-minute call any time, or see how I work with buyers on my buyer page.
FAQ
Are closing costs negotiable in Maryland?
Some are. Deed tax splits and seller credits can be negotiated in the contract. Third-party fees like the appraisal are not, but lender fees can vary between lenders.
How much cash should I plan to bring to closing?
Your Loan Estimate gives the best number. Expect it to include your down payment plus closing costs and prepaids. Costs depend on the loan, the price and the county.
Can I roll closing costs into my loan?
Sometimes, depending on the loan type and appraised value. Ask your lender.
Does the seller always pay the transfer tax for first-time buyers?
Maryland law sets a default, but a contract can change it. Read that paragraph before you sign.
When do I find out my final closing costs?
Lenders must give you a Closing Disclosure at least three days before settlement, so you'll see final numbers before you sign. [VERIFY: federal TRID timing.]
I'm a REALTOR(R) with Samson Properties, not a tax or legal advisor. For your exact numbers, check with your lender and title company.
Recent Posts