Featured Listing
1213 S Pointe Dr, Hagerstown
5 Beds | 3 Baths | 1,788 Sq Ft | 0.34 Acres
An all-brick rambler in South Pointe with five bedrooms and three full baths on one level. New carpet, fresh paint, and updated systems and appliances. I'm the listing agent, so you can ask me anything.
See the homeCall or text MichaelListing courtesy of Michael Wade, Samson Properties. Source: Bright MLS #MDWA2040260.
Featured Rental
1346 Cox Cove Ct, Stoney Beach
3 Beds | 2.5 Baths | 1,554 Sq Ft | For Rent
A brick-front townhome overlooking Cox Creek in Stoney Beach. Hardwood floors, stainless appliances, a deck, and a walkout lower level with its own fireplace. I'm the listing agent, so you can ask me anything.
See the homeCall or text MichaelListing courtesy of Michael Wade, Samson Properties. Source: Bright MLS #MDAA2159066.
Most agents tell you they're different. Here's the system — you can see every piece of it.
Every client gets the same documented process: the same reports, the same checklists, the same follow-through. Nothing improvised, nothing hidden.
Twelve steps from pre-approval to keys. You'll always know which one you're on.
Conventional, VA, FHA and Maryland Mortgage Program buyers — the roadmap is the same, and so is the attention.
BOOK A 15-MINUTE BUYER CALL READ THE FULL BUYER PROCESS →- STEP 1–3Plan & pre-approvalBudget, loan options and a lender introduction, so you shop with a real number.
- STEP 4–6Search & value checksA personalized search, and a written value check on each home before you tour it.
- STEP 7–9Offer to inspectionOffer strategy built on local data, then an inspection report review with you.
- STEP 10–12Closing & afterEvery contract deadline on your calendar, keys in hand, and a home value report twice a year.
A forty-item report is a list. You get a plan.
Inspection reports are long and every item reads like a problem. After yours, you get a written debrief: every finding sorted by what actually matters, a cost range for each real fix, and the request we send to the seller.
- 1
Safety items firstOpen wiring, doors and railings that don't do their job. Small fixes, and the anchor of any request.
- 2
Active leaksWater where it shouldn't be today. Small now, expensive if ignored.
- 3
Water getting toward the houseFlashing, downspouts, grading. Each one is how small items become expensive ones.
- 4
Everything else is upkeepMaintenance, cosmetic and "monitor" items go on your first-year list, not into the negotiation.
- Cost ranges come from published local pricing and are labeled that way — they are not contractor estimates. Credit or repairs is your call; I'll show you the trade-offs.
FEATURED LISTINGS

3 Beds4 Baths2,016 SqFt
13045 SHEFFIELD MANOR DR, Silver Spring, MD 20904
MLS# MDMC2263010
Listed by Samson Properties


5 Beds3 Baths1,788 SqFt
1213 S POINTE DR, Hagerstown, MD 21740
MLS# MDWA2040260
Listed by Samson Properties

3 Beds3 Baths1,554 SqFt
1346 COX COVE CT, Stoney Beach, MD 21226
MLS# MDAA2159066
Listed by Samson Properties

3 Beds3 Baths1,952 SqFt
10334 PROCERA DR, Rockville, MD 20850
MLS# MDMC2262176
Listed by Samson Properties
NEIGHBORHOOD GUIDES


Rent less. Own sooner. Build wealth where you live.
A six-month plan for renters: rent-vs-buy math for your town, credit and savings targets, and the down payment programs you may qualify for — including the Maryland Mortgage Program and DC Open Doors.
WHAT NEIGHBORS SAY
- Michael made my home buying experience wonderfully smooth. He’s a wealth of knowledge and sweetness. His professionalism is top-tier!!!
- Michael was a pleasure to work with while buying my home. He is knowledgeable and patient. He makes the home buying process as stress free as possible as he is an excellent problem solver. I look forward to working with him in every real estate transaction going forward. He is the best!
- Throughout the home-buying process, Michael was able to keep us on track, provided insightful critiques of each of the properties we toured, and--most importantly--helped us to get a thorough inspection and multiple contractor quotes on a very short time frame. With perfect efficiency, he is able to negotiate with sellers, lenders, and contractors to get us to closing. Within the space of the inspection period, in addition to the inspector, Michael was able to connect with a reputable roofer and HVAC expert to address specific concerns we had about the property. The home itself was gorgeous and off our radar. Spur of the moment, Michael was able to find it and get us in for a tour. We fell in love with the home immediately. I would recommend him as an agent for any buyer, any day
- TMorrisWe had an absolutely outstanding experience working with Michael and cannot recommend him highly enough to anyone buying or selling a home! From beginning to end, he delivered exceptional customer service, communicated clearly and consistently, and made what can often be a stressful process feel smooth and completely manageable. What truly set him apart was his ability to use real data and strong market insight to shape our strategy, which gave us total confidence in every decision. Thanks to his expertise, our house sold in just 2.5 days — an amazing result that far exceeded our expectations! We’ve worked with Michael twice now, and we honestly would not consider anyone else to handle a home purchase or sale. If you want a knowledgeable, responsive, and truly results-driven real estate agent, Michael is the one you want in your corner.
- Over text messages, emails, and phone calls, I have never met a more communicative realtor. Michael was out in front of issues before they arose, and presented detailed plans and solutions at the same time he alerted us to problems. He accurately assessed the home's value and managed to get us an offer over listing price. We would absolutely recommend Michael, and would use him again if the opportunity arose.
- NataliaMy husband and I have bought many properties and have dealt with a variety of agents in the process, but Michael Wade is hands-down the best agent we've ever had. His professionalism and attention to detail is second to none. I never had a doubt that he was doing his best to get us the best deal at the property we chose. He wasn't pushy and we always felt that he had our best interests in mind. The next time we buy or when we're finally ready to list our own house we will no doubt return to Michael!
- Parviz KhalikovWe recently bought a house with Michael Wade, and the experience was outstanding. He guided us through every step with professionalism and patience, making the entire process feel organized and stress free. Michael was always available to answer questions, explain details, and advocate for our best interests. His knowledge and communication gave us confidence from start to finish. We’re grateful for his support and highly recommend him to anyone looking to buy a home.
- Bryant DespeauxMichael guided us through the entire process from start to finish. He was extremely communicative and always available to answer our questions and address any concerns. His use of data to determine a home’s value and predict how quickly it would sell was incredibly helpful in our decision-making process. Michael knew when to fight for us and when to offer thoughtful, honest advice. He is the most professional and knowledgeable realtor I’ve ever worked with, and I would highly recommend him to anyone looking to buy or sell a home.
- I recently purchased a home with Michael Wade as my realtor and had an outstanding experience. Michael stood out for his honesty, providing candid feedback without pressure, his data-driven approach backed by market research and comparable sales analysis, and his exceptional work ethic—he was responsive, proactive, and went above and beyond throughout the entire process. If you're looking for a real estate agent who combines integrity, analytical expertise, and dedication, I highly recommend Michael Wade. ⭐⭐⭐⭐⭐
- Michele C.Michael Wade handled the sale of my elderly mother’s home with a rare combination of expertise, ethics, efficiency, and genuine compassion—in short, unparalleled excellence. Although this platform only allows for five stars, our experience with Michael genuinely deserved ten. From our first conversation through closing, he was completely transparent, exceptionally well prepared, and unfailingly gracious and patient—especially with my mother as a senior. He is deeply knowledgeable about the industry and—perhaps because he was once a teacher—has a gift for making complex information easy to understand, which made a challenging process feel manageable for our family. Michael operates with the highest ethical standards. He clearly explained every option, never pressured us, and made each step feel clear and accessible. His communication was consistently superb—timely updates, quick responses, and proactive outreach meant we always knew what was happening and what to expect next. Even though we knew he had other clients and many demands on his time, he somehow made us feel like we were his only clients. We could not recommend Michael more highly. He is an extraordinary real estate professional—and an even more remarkable human being—and anyone would be fortunate to work with him.
- Robert Jackman GordonI’ve both bought and sold a home with Michael, and he is by far the best realtor I’ve ever worked with. From the very first meeting, it was clear he truly cared about our goals and was willing to do whatever it took to help us achieve them. Michael fought hard for us in both transactions — negotiating strongly on our behalf, keeping us informed every step of the way, and going well beyond what most agents would ever do. He’s professional, responsive, and incredibly knowledgeable, but what really sets him apart is how much he genuinely looks out for his clients. We always felt like we had a true advocate in our corner. If you want a realtor who combines expertise, integrity, and relentless dedication, Michael is the one you want on your side. I couldn’t recommend him more highly.
- C. Jackman-GordonMichael is a wonderful agent. He listens to his clients and is extremely dedicated to providing them with what they are looking for. I first worked with him when I was buying my house and then worked with him when I was selling the house when we moved-out of-state Michael always provides concise, realistic, and up-to-date information so that his clients can make the decision that best suits their needs. He is honest, transparent, and always ready to provide solutions with the data to support his findings. His response times are very fast and his expertise and knowledge are unparalleled. If you somehow happen to find something he hasn’t encountered before, he knows exactly where to get the answers. He is the best real estate agent I have ever worked with. I have bought and sold houses in 5 different states due to moving for work and the experience of buying and then selling with him was far above any others I have worked with.
- Karol NakazziMichael was incredible in helping me find the perfect home that truly matches my personality. He took the time to understand my tastes and preferences and delivered exactly what I was looking for. Throughout the entire process, he kept me informed, clearly explaining each step so I always knew where we stood. His professionalism, patience, and attention to detail made the experience seamless and enjoyable. I couldn’t have asked for a better guide in finding my home.
- Anindita SahaWe couldn’t ask more anything from Micheal as our buyer agent.
- Bob KirchnerMichael Wade really impressed us on his level of energy, enthusiasm, knowledge and positive attitude. With his help we were able to quickly overcome all obstacles and issues for a quick sale. His polite professionalism and communications really help alleviate stress during the process and consider ourselves to be very fortunate to have had him handle our home sale. We would be happy to work with him in the future if the need arises.

Soldier. Teacher. Now your advisor on the biggest purchase you'll make.
I spent 13 years in the U.S. Army, finishing as a Civil Affairs Team Sergeant — a job built on planning, accountability and getting people through complicated situations. Then I spent three years as a special educator in Prince George's County Public Schools, where the work was explaining hard things clearly and never leaving anyone behind.
Real estate uses both. For nearly a decade I've helped buyers and sellers across Maryland and Washington, D.C. with Samson Properties, using a written process, real data and plain talk.
FROM OUR BLOG
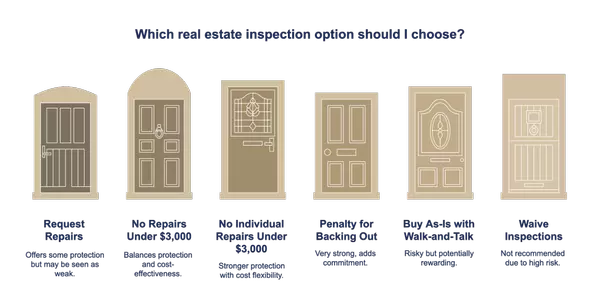
What Do I Have to Disclose When Selling a House in Maryland?
In Maryland, you have to give the buyer either a Residential Property Disclosure Statement or a Residential Property Disclaimer Statement. Even if you sell "as is," you must disclose latent defects you actually know about. A past leak or mold you know about is something to talk through with me and,
How Do I Time Selling My House and Buying the Next One?
There are three basic paths: sell first, buy first, or line up both at once. Most people aim for as little overlap as possible, using tools like a home sale contingency, a rent-back after closing, an extended closing date, or short-term financing. The right one depends on how much cash you have, how
How Does an Assumable Mortgage Work?
An assumable mortgage lets a qualified buyer take over the seller's existing loan, including the interest rate, remaining balance, and remaining term. It's mostly available with FHA, VA, and USDA loans. It can be a great deal when the seller's rate is well below today's rates, but you still have to
Follow Me on Social

View More
Start with a conversation.
Fifteen minutes, no pressure. Tell me where you are and I'll show you what the next steps look like.