What Due Diligence Should I Finish During the Contingency Period?

During the contingency period, you should finish the home inspection and any specialist follow-ups, confirm your financing, review the seller's disclosures and the title work, and get a homeowners insurance quote. Then decide whether to move forward, ask for repairs or credits, or walk away under the terms of your contract. The deadlines are in your contract, so get them on a calendar the day you're under contract.
Start with the dates
Your contract sets the deadlines for each contingency, such as inspection, financing, and appraisal. Missing a deadline can change your rights. Ask your agent to write every date down and confirm the exact time each one ends. If you need more time, ask early. Extensions have to be agreed to in writing.
Inspections
- General home inspection. Book it right away. Inspectors can be busy. Go to the inspection if you can. You'll learn more walking through with the inspector than from the report alone.
- Specialists the inspector recommends. If the report points to a roof, chimney, electrical panel, foundation, or HVAC concern, schedule that specialist quickly.
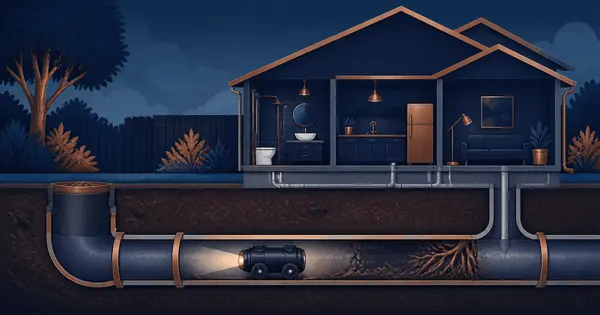
- Sewer scope. On older homes, a camera look at the sewer line can find problems that are expensive to fix.
- Radon. Radon testing is common in Maryland. Ask your inspector about it.
- Well and septic. If the property has them, these usually need their own testing.
- Wood-destroying insects. Lenders often require a termite inspection. Ask your lender.
- Lead paint. For homes built before 1978, federal rules give buyers an opportunity to test for lead-based paint. Ask your agent about timing.
You choose your own inspectors. I can share names of companies I know, but the choice is always yours.
Financing
Stay in close touch with your lender. Send documents fast. Don't open new credit, switch jobs, or move large sums without checking first. Ask for updates on the appraisal and underwriting, and what conditions are still open.
Appraisal
Your lender orders it. If it comes in below the price, you can talk with your agent about renegotiating, bringing more cash, or using your contract protections. This is why it helps to know your appraisal contingency terms in advance.
Seller disclosures and title
- Read the seller's disclosure or disclaimer statement. In Maryland, sellers generally provide a property condition disclosure or disclaimer. It's worth reading line by line.
- Review the title commitment. Your title company searches for liens, easements, and ownership issues. Ask what the exceptions mean.
- Check HOA or condo documents. Look at fees, special assessments, rental rules, and reserves.
Insurance and ongoing costs
Get homeowners insurance quotes before the contingency ends. Some homes, like those with older roofs or certain systems, can be more costly to insure. Also ask about flood zone status, property taxes, and utility costs. These affect your monthly payment.
Make your decision
After the reports are in, you generally have a few options: proceed as is, ask for repairs, ask for credits, or terminate if your contract allows. Your agent can help you prioritize. Safety and big-ticket systems usually matter more than cosmetic items. The call is yours.
FAQ
Can I ask for everything on the inspection report?
You can ask. Sellers usually respond best to a focused list of the important items.
What if I can't finish in time?
Ask your agent about an extension addendum before the deadline, not after.
Should I skip inspections to compete?
That's a personal risk decision. I'd talk through the possible costs with you before you decide.
Do I need to attend the inspection?
It isn't required, but it's very useful.
Who pays for inspections?
The buyer typically pays for their own.
Next step
Buying in Maryland and want to talk it through? See my buyer resources, or contact me. Want to run your numbers with me? Grab a free 15-minute call at calendly.com/michaelwaderealtor/15min. No pressure.
Recent Posts